how-to
Teaching Children About Money Management: 7 Steps
Table of Contents
- Step 1: Start Early with Age-Appropriate Financial Milestones
- Step 2: How to Explain Needs vs Wants to a Child
- Step 3: Set Up Allowance Systems for Financial Education
- Step 4: Use Financial Literacy Activities for Kids to Make Learning Stick
- Step 5: Teaching Kids About Compound Interest Without the Jargon
- Step 6: Teaching Children About Money Management in the Digital Age
- Step 7: Teaching Children About Money Management with Neurodiversity in Mind
- Common Mistakes to Avoid When Teaching Children About Money Management
- Frequently Asked Questions
Last Updated: September 29, 2026
Step 1: Start Early with Age-Appropriate Financial Milestones
Teaching children about money management works best when it starts young and grows with the child: a four-year-old can learn that coins buy things, a fourteen-year-old that compound interest builds wealth.
Here's a simple milestone map to follow:
- Ages 3-5: Name coins, play store, understand that money is exchanged for goods
- Ages 6-8: Count money, earn a small allowance, split cash into save and spend jars
- Ages 9-11: Open a savings account, compare prices at the store, set a short-term goal
- Ages 12-14: Build a simple budget, track spending, learn the difference between needs and wants
- Ages 15-18: Get a first job, understand taxes, learn investment basics
Step 2: How to Explain Needs vs Wants to a Child
Needs vs wants is the difference between what you must have to live and stay safe, and what you'd simply like to have. Food, shelter, clothing, and medicine are needs; a video game, a second pair of sneakers, and checkout candy are wants. Kids test that line constantly, and that's a good thing.
- Ask: "Would we be okay without this for a week?"
- Ask: "Is there a cheaper way to get the same thing?"
- Ask: "What would we give up to buy this instead?"
Step 3: Set Up Allowance Systems for Financial Education
An allowance is a regular sum of money a child receives, often tied to chores or a set schedule, that gives them real practice managing cash. The best systems are consistent, small, and come with freedom to make mistakes.
Pick a system that matches your family's values
You have three main options, and none is objectively "right", the choice depends on what you want the money to teach.
| System | How It Works | Best For | Trade-off to Know |
|---|---|---|---|
| Chore-based | Pay per completed task | Kids who need motivation to help | Can turn shared duties into a transaction |
| Base allowance | Fixed weekly amount, no strings | Teaching that family chores are shared duties | Kids may not connect money to effort |
| Hybrid | Small base plus bonus for extra jobs | Most families, ages 8+ | Requires you to keep two categories straight |
Set the amount and the schedule
There's no universal number, but a common pattern is roughly one dollar per week per year of age, a 10-year-old gets about $10 weekly. What matters more than the amount is predictability: same day, same amount, every week. That's what lets a child plan.
Build the split before the spend
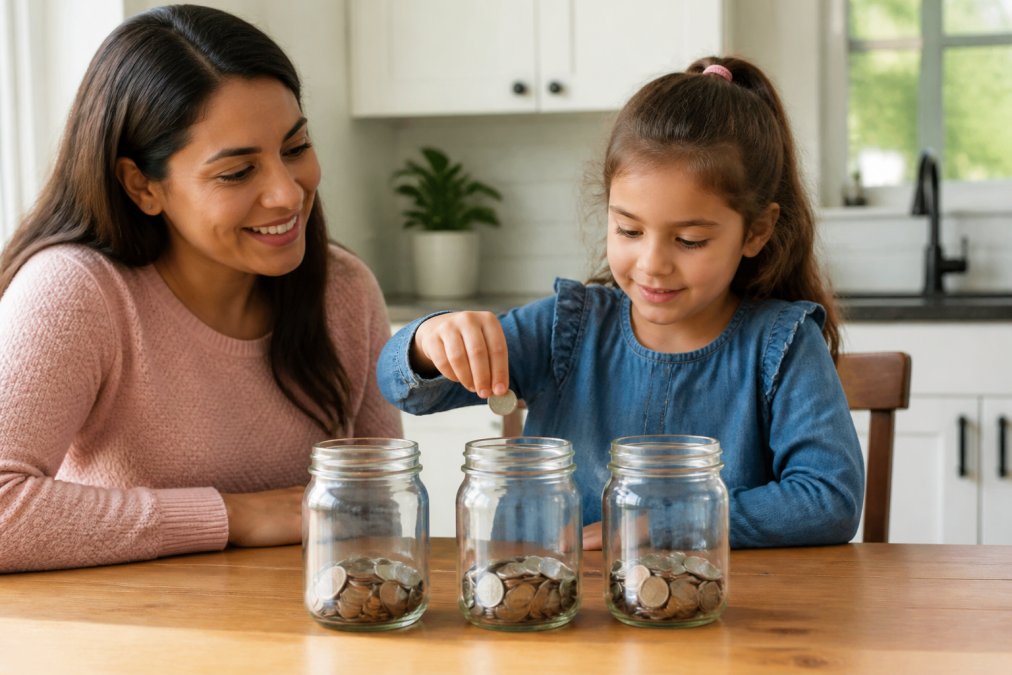
The moment money lands, it should be divided. For younger kids, use three jars: Save, Spend, Give. A common starting ratio is 50/40/10, though some families use equal thirds. The numbers matter less than the habit of splitting before spending.
Let them fail, but debrief the failure
The key rule: once you hand over the money, let them decide. If your nine-year-old blows it all on stickers, that's a cheap lesson now and an expensive one avoided later. But don't stop at the loss. Ask three questions afterward:
- What did you hope this would do for you?
- How do you feel about it now?
- What would you do differently next time?
Handle raises, pauses, and "I want more"
Revisit the allowance once a year. Tie increases to new responsibilities, not inflation alone, a 13-year-old managing their own clothing budget needs more money and autonomy. If a child asks for a raise mid-year, treat it like a real negotiation: they make the case, you decide.
Step 4: Use Financial Literacy Activities for Kids to Make Learning Stick
Financial literacy activities for kids work because they turn abstract ideas into things children can touch, count, and feel. Lectures don't stick. Games do.
Here are activities that actually land:
- The three-jar system: Label jars Save, Spend, and Give. Every allowance gets split across all three.
- Store role-play: One person is the shopkeeper, one is the buyer. Practice making change.
- Price detective: At the store, have your child find the best price per unit on two similar items.
- Goal chart: Pick a toy or game, draw a progress bar, and color it in as savings grow.
- Family budget night: Once a month, show your kids a simple version of the household spending plan.
Consumer Financial Protection Bureau's money activities for kids
Step 5: Teaching Kids About Compound Interest Without the Jargon
Compound interest is when the money you save earns its own money, and then that new money earns money too. Skip the formulas. Use a story instead.
- Start with a small amount they can track
- Check the balance together once a month
- Mark the growth on a chart or calendar
- Talk about how time does the heavy lifting
Step 6: Teaching Children About Money Management in the Digital Age
Money is invisible now. Kids see you tap a card or click "buy" and something arrives two days later. That gap between action and payment hides how spending really works, the biggest blind spot in most money guides for kids, which still assume cash and piggy banks.
Close the gap with these concrete steps.
Make the invisible visible
- Show the transaction history. After an online purchase, open your banking app and show your child the money leaving the account. Do this every time for a month. The repetition is what builds the connection.
- Narrate card taps out loud. "That's $14 leaving our account right now." Kids who hear the number attach a cost to the beep.
- Print one statement a month. Highlight every subscription, every auto-renewal, every app purchase. Let your child see how small charges add up.
Teach the mechanics of in-app purchases
Games are engineered to make spending frictionless, a design choice, not a conspiracy. Name it out loud. Show your child how a "free" game makes money: gems, coins, extra lives, ad-free upgrades. Then walk through the settings together:
- Turn off in-app purchases at the device level (both iOS and Android have this in parental controls).
- Require a password for every purchase, not just the first one.
- Disable saved card details in the app store.
- Review the "subscriptions" list together once a month and cancel anything unused.
Federal Trade Commission's guidance on kids and in-app purchases
Set up a real digital wallet with real limits
Around age 11-13, many families move from cash to a prepaid card or parent-controlled debit app, the digital equivalent of handing over the allowance, with the same rules:
- Cap the weekly load. If the allowance is $15, load $15. No overdraft, no top-up on demand.
- Separate the buckets. Many apps let you split a load into Save, Spend, and Give. Use that feature so the split habit survives the move to digital.
- Make them check the balance before buying. Not after. Before. This one habit prevents most overspending.
- Review the app's transaction feed together weekly. Five minutes, same day each week.
Talk about ads, influencers, and "buy now, pay later"
Kids are targeted by financial products earlier than most parents realize. Buy-now-pay-later buttons appear at checkout on sites teens use. Influencers promote products without disclosing sponsorships. Skins, loot boxes, and battle passes are designed to feel urgent.
Practice with a spending tracker they actually use
A notebook works. So does a notes app, a spreadsheet, or the tracker inside a kids' banking app. The format matters less than the ritual: log every purchase the same day, categorize it, and review the week together. After a month, patterns appear, and patterns are where the real conversations start.
Step 7: Teaching Children About Money Management with Neurodiversity in Mind
Standard money advice doesn't fit every child. Kids with ADHD, autism, or learning differences often need clearer rules, more repetition, and fewer choices at once.
What helps in practice:
- Make it visual. Use jars, charts, or colored envelopes so saving is something they can see.
- Keep rules short. One rule at a time beats a list of five.
- Build routines. Same day, same amount, same split every week.
- Reduce choices. Two options, not ten, at the store.
- Celebrate small wins. Progress matters more than perfection.
Common Mistakes to Avoid When Teaching Children About Money Management
The biggest mistake is waiting until kids are teenagers to start. By then, habits are set and the stakes are higher.
Other traps to watch for:
- Bailing them out every time. If you replace every lost dollar, they never feel the cost.
- Making money a taboo topic. Silence teaches kids that money is scary, not manageable.
- Being inconsistent. An allowance that shows up some weeks and not others teaches nothing.
- Skipping the giving piece. Charitable giving teaches kids that money can do good, not just buy things.
- Forgetting inflation. A dollar today buys less than it did a decade ago. Explain purchasing power in simple terms so kids understand why saving alone isn't enough.
OECD's financial literacy framework for youth
Frequently Asked Questions
At what age should you start teaching children about money management?
You can start as early as age 3 with simple concepts like naming coins. By age 5, children can begin sorting needs vs wants. Between 7 and 10, introduce allowances and saving goals. Teen years are ideal for compound interest and digital spending. The key is matching the lesson to their developmental stage, not waiting for one perfect age.
What is the 50/30/20 rule for kids?
The 50/30/20 rule is a budgeting framework: 50% for needs, 30% for wants, and 20% for savings. For children, you can simplify it to three jars or envelopes. If a child receives $10 allowance, $5 goes to needs (like school supplies), $3 to wants (a toy), and $2 to savings. This builds a spending plan habit early.
How do I explain the difference between needs and wants to a child?
Use concrete examples from their daily life. A need is something you must have to live and be safe, like food, water, shelter, and clothing. A want is something nice to have, like a video game or candy. Try a sorting game: give them pictures or items and ask them to place each in a 'need' or 'want' box. Discuss why each choice matters.
What are the best ways to teach kids about saving and spending?
Give them real money to manage through an allowance. Set short-term savings goals, like a toy they want in four weeks. Use a savings account to show interest. Let them make small spending mistakes. Pair saving with giving to build generosity. And model these behaviors yourself, because children learn more from what you do than what you say.
FAQ
You can start as early as age 3 with simple concepts like naming coins. By age 5, children can begin sorting needs vs wants. Between 7 and 10, introduce allowances and saving goals. Teen years are ideal for compound interest and digital spending. The key is matching the lesson to their developmental stage, not waiting for one perfect age.
The 50/30/20 rule is a budgeting framework: 50% for needs, 30% for wants, and 20% for savings. For children, you can simplify it to three jars or envelopes. If a child receives $10 allowance, $5 goes to needs (like school supplies), $3 to wants (a toy), and $2 to savings. This builds a spending plan habit early.
Use concrete examples from their daily life. A need is something you must have to live and be safe, like food, water, shelter, and clothing. A want is something nice to have, like a video game or candy. Try a sorting game: give them pictures or items and ask them to place each in a 'need' or 'want' box. Discuss why each choice matters.
Give them real money to manage through an allowance. Set short-term savings goals, like a toy they want in four weeks. Use a savings account to show interest. Let them make small spending mistakes. Pair saving with giving to build generosity. And model these behaviors yourself, because children learn more from what you do than what you say.